Home » Bad Credit Home Loan Refinancing
Bad Credit Home Loan Refinancing
Credit issues shouldn’t define your future. If you’re thinking about refinancing your home loan, BrightCredit can help you explore what’s possible.
We’ll take the time to understand your circumstances and help you find a way forward.
Worth Another Look
Is Your Home Loan Still Working for You?
Your current home loan might no longer suit your circumstances. Perhaps you’re looking for more manageable repayments, a different loan structure or simply a fresh start.
Refinancing with bad credit can be more complicated, but the equity in your home and your current financial position may open up options worth considering.
Different Starting Points
Does This Sound Familiar?
You might be ready to refinance, or simply wondering whether a change is worth exploring. Here are some situations we commonly help with.
1. Low Credit Score
Your credit score has taken a hit, and you’re unsure whether refinancing is still possible.
2. Defaults or Missed Payments
You’ve experienced repayment difficulties and want to know how they might affect your options.
3. Repayments Under Pressure
Your current mortgage repayments are becoming harder to manage, and you’re looking for a way forward.
4. Previously Declined
A bank has turned down your refinancing application, and you’d like to explore other possibilities.
The Details Behind the Decision
It's All About Balance
Finding a refinancing option is one thing. Making sure it works for you is just as important. Lower repayments might ease financial pressure, but a longer loan term or higher interest rate may increase the overall cost.
We’ll compare the numbers against your existing mortgage and explain the trade-offs, so you can understand whether refinancing is genuinely worthwhile.
Important Factors
What Shapes Your Refinancing Options?
Your refinancing options need to work around your financial situation. Here are some of the things that matter.
Property Value & Equity: The value of your home compared with what you owe can influence your refinancing options.
Mortgage Repayment History: Lenders may review how you’ve managed your existing mortgage, including missed or late repayments.
Income & Expenses: Your earnings, living costs and existing debts help determine whether a new loan is affordable.
Credit History: The age, severity and status of defaults or other credit issues can affect your options.
Existing Loan Terms: Your outstanding balance, fixed-rate arrangements and exit costs can influence whether switching makes sense.
Refinancing Purpose: Your reasons for refinancing can influence which loan options are available for your circumstances.
The BrightCredit Advantage
Refinance Without the Runaround
Refinancing can easily end up in the too-hard basket, particularly when credit issues are involved. Between the paperwork and lender requirements, it’s understandable why people put it off.
We take much of that work off your plate. From preparing your application to dealing with lenders and organising the switch, we’ll help keep things moving.
You’ll have someone you can speak to directly, who understands your circumstances and keeps you informed as things progress.
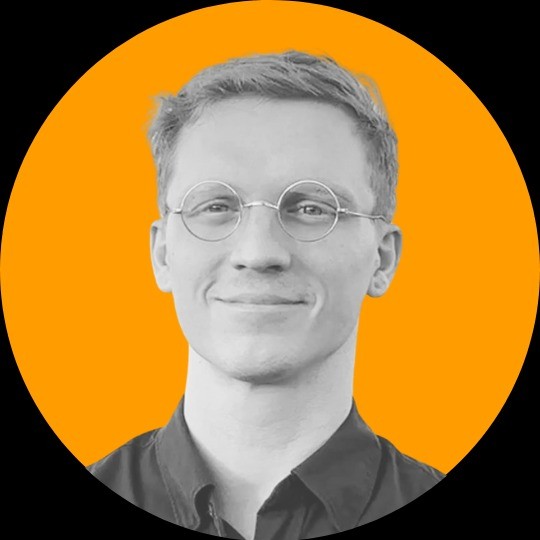
A Note From Tom
I’m Tom Raeder, founder of BrightCredit and a finance broker focused on borrowing situations that aren’t straightforward.
If you’re considering refinancing with credit issues, I’ll take the time to understand your circumstances and what you’re hoping to achieve.
I’ll explain the options in plain English, including what’s realistic, what could get in the way and whether refinancing is worth pursuing.
I’m an authorised credit representative (CRN 580839) of Purple Circle Financial Services Pty Ltd, Australian Credit Licence 486112, and an MFAA Accredited Broker (Member 204039). You can verify my details on ASIC’s Professional Registers or view my profile on the MFAA Find a Broker directory.
More Information
Frequently Asked Questions
An initial enquiry with BrightCredit isn’t the same as a formal loan application. If you proceed, a credit check may be required and recorded on your credit report. We’ll explain what’s involved before you apply.
Not always. Some lenders may consider applications with outstanding defaults, depending on their nature, amount and your current financial circumstances.
Equity requirements vary between lenders. Your property’s value, outstanding mortgage balance and credit history can all influence your options.
Depending on your circumstances, costs may include discharge fees, application fees, property valuations or fixed-rate break costs. We’ll explain any applicable costs before you proceed.
Your Next Step
Find Out Where You Stand
You don’t need to have everything figured out before getting started. Tell us a little about your current mortgage and what you’d like to change.
We’ll review your circumstances and get in touch to discuss refinancing options worth considering.